Last Updated on 25/09/2026 by Nicole Alba
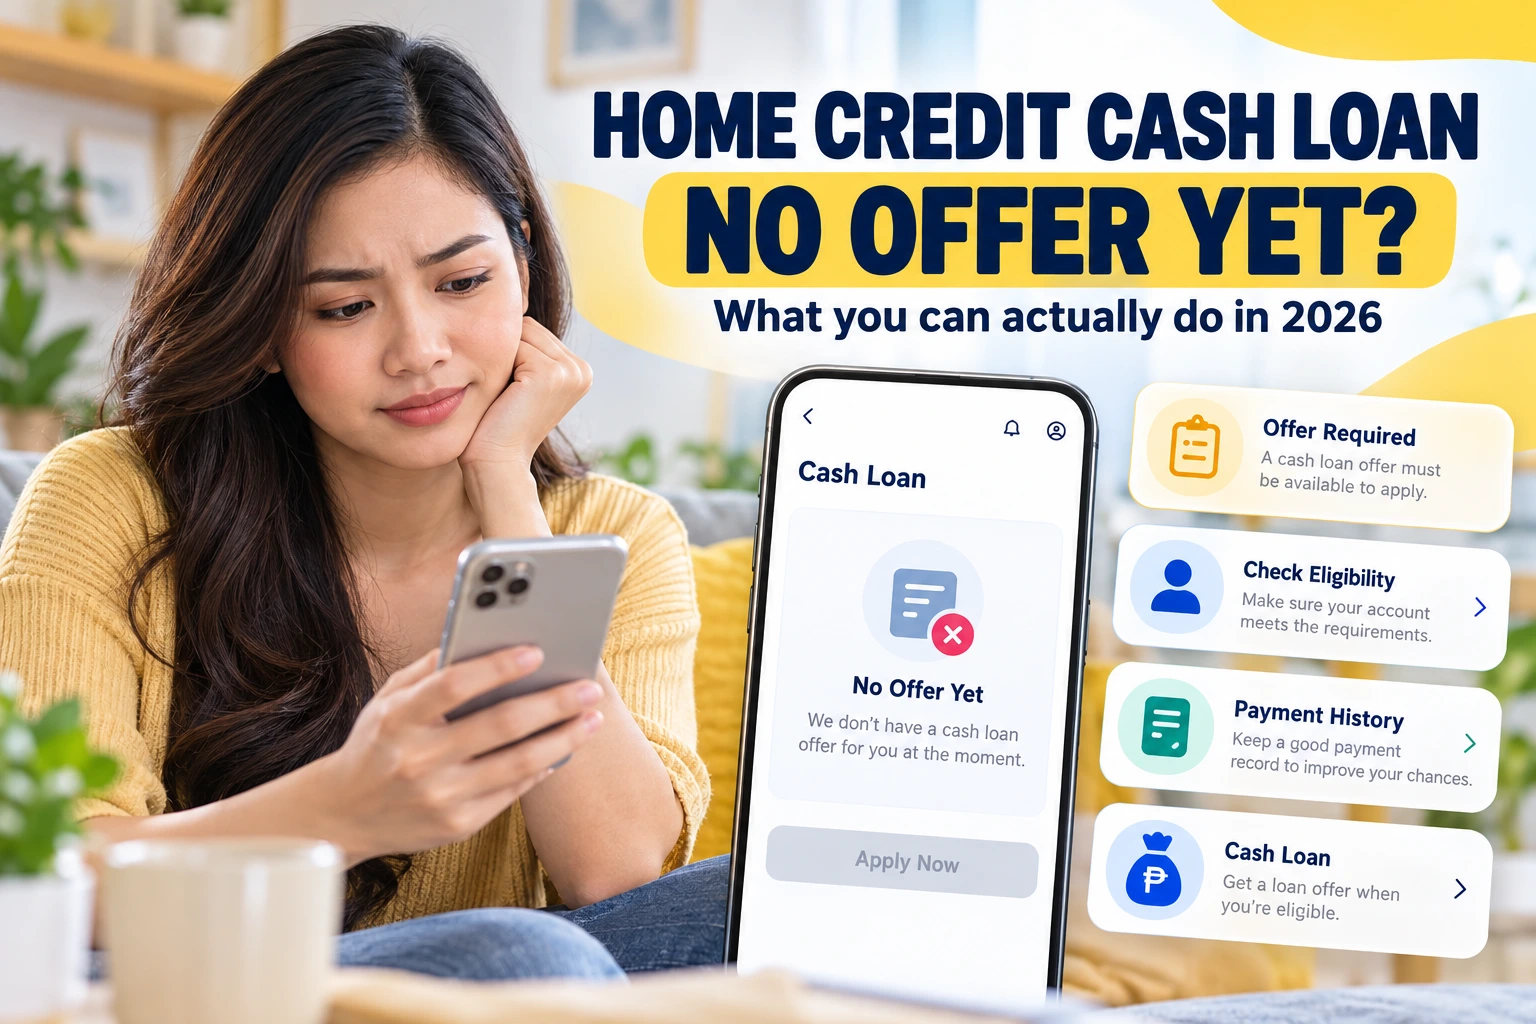
If you opened the Home Credit app expecting to see a cash loan but found no Cash Loan banner under “Offers for You,” the most important point is simple: Home Credit does not currently allow customers to submit a normal Cash Loan application without first receiving an eligible offer. Its July 31, 2026 Cash Loan FAQ states this directly. Home Credit says offers may become available based on previous transactions and payment history, but completing a previous loan or paying on time does not create an automatic right to another offer.
This distinction matters because a Cash Loan “offer” is also not the same thing as final approval. Once an offer appears, the borrower still chooses an amount and term and submits an application for credit assessment. Home Credit’s own application instructions say the selected amount and term are still subject to processing before approval.
This review uses a source-first approach and does not claim that we personally borrowed from Home Credit, received an offer, or tested an application unless such first-hand evidence exists.
| Borrower question | Current finding | Why it matters |
|---|---|---|
| Can you apply without an offer? | No. Home Credit says Cash Loans are exclusive to customers with an offer. | There is no official workaround that bypasses eligibility. |
| Who operates Home Credit? | HC Consumer Finance Philippines, Inc.; SEC Reg. No. CS201301354, Certificate of Authority 1071. | This identifies the legal financing company behind the brand. |
| Who can potentially receive an offer? | Existing Home Credit customers who have previously used a Product Loan may qualify; payment history can affect eligibility. | First-time users should not expect an immediate Cash Loan option. |
| Cash Loan amount | Published range is ₱3,000 to as much as ₱150,000, but the maximum is personalized. | ₱150,000 is not a guaranteed available limit. |
| Is an offer guaranteed approval? | No. Selecting an amount and term still starts an application that must be processed for approval. | Do not spend or commit money based only on seeing an offer. |
| Published interest | Home Credit’s disclosure page currently shows 1.49% – 8.99% nominal interest per month, while its Cash Loan page says rates start at 2.32% per month. | The actual Loan Disclosure Statement is more important than a headline rate. |
| Processing fee | Up to ₱500, subject to the actual contract or an applicable promotion. | Fees affect the real cost of borrowing. |
| Cash-out | Bank transfer or cash pickup are published options. | Cash pickup can carry an additional fee. |
| Privacy | The app may request access to contacts, transactional messages, device information, files and location with consent. | Review permissions rather than accepting them automatically. |
Can you apply for a Home Credit Cash Loan without an offer?
No. Home Credit’s current Cash Loan FAQ says a borrower cannot apply without an offer. Its stated route is to become an eligible Home Credit customer, wait until a Cash Loan offer is generated, and then submit an application through an official channel.
This answers the main search question more narrowly than many generic “how to apply” guides. Downloading the app, registering an account, visiting a partner store or calling customer service does not by itself create a Cash Loan entitlement.
Home Credit says Cash Loan offers may become available according to previous Home Credit transactions and payment history. Its guidance tells customers to start with a Product Loan, make installments consistently and check the app for future offers.
For first-time Home Credit users, the company’s May 2026 eligibility guide is even clearer: the Product Loan is described as the loan available to first-time users, while Cash Loans require previous use of a Home Credit Product Loan.
That means websites, Facebook pages, agents or individuals claiming they can “activate” or “unlock” a Home Credit Cash Loan for a fee should be treated cautiously. An official offer should be visible through Home Credit’s authorized channels rather than purchased from a third party.
What should you do when there is no Cash Loan offer?
There is no published button or manual application route that overrides the missing offer. The practical route is to keep your Home Credit information accurate, maintain your existing obligations properly and periodically check the official app or eligibility page. None of those steps guarantees that an offer will appear.
Home Credit says customers with a good payment record may qualify after completing a Product Loan and making their monthly payments on time. The wording “may qualify” is important: it is not a promise that every borrower who finishes a loan will receive Cash Loan access.
A recent App Store review illustrates this distinction. One reviewer reported finishing a Product Loan after paying on time but still not receiving another loan or Cash Loan offer. That is an individual borrower report, not statistical evidence about approval rates, but it is consistent with Home Credit’s published position that good repayment history can improve eligibility without guaranteeing a new offer.
Home Credit also says its systems use information for credit verification, credit scoring and automated loan processing. Its privacy notice says analytics and automated technologies may use factors such as transaction history, product usage and engagement for personalization and recommendations. The company does not publicly disclose a complete formula that tells a customer exactly how to trigger a Cash Loan offer.
So, paying an existing loan early, repeatedly opening the app or contacting an agent should not be treated as a guaranteed technique for producing an offer.
How do you check whether Home Credit has finally given you an offer?
Log in to the official Home Credit app and look beneath “Offers for You” or open the Loans tab. Home Credit may also communicate eligible Cash Loan offers through SMS, email, phone calls or push notifications.
Be careful with messages claiming to represent Home Credit. Instead of following an unfamiliar link immediately, verify that the same offer appears inside your official account or use contact information published by Home Credit.
Its current Cash Loan page also provides an eligibility check and says customers can use the website or app to see whether they qualify for an offer.
An offer should also be read as permission to apply, not a promise that cash is already yours. Home Credit’s application guide explicitly says the requested amount and repayment term must still be processed for approval.
How do you apply once a Cash Loan offer appears?
Once eligible, borrowers can apply through the Home Credit app, a partner store or the telephone channel identified in an official offer. The app process includes choosing the amount and term, completing identity and financial information, undergoing approval and electronically signing the loan agreement.
The current app flow can be summarized as follows:
- Open the Cash Loan banner in the Home Credit app and select “View Details.”
- Choose from the loan amount and repayment terms available within your personalized offer.
- Review optional value-added services such as Borrower Protection or Loan Extra Care. Home Credit states that these services are not mandatory.
- Select your loan purpose and preferred cash-out method.
- Complete the application. Home Credit says borrowers may be asked for a selfie, valid-ID photo, personal information, income information and housing details.
- If approved, review the approved amount, repayment terms, disclosure documents and agreement before signing electronically using the OTP sent to your registered mobile number.
- Wait for confirmation that the loan can be claimed or disbursed.
This sequence also explains why an offer should not be confused with approval. Credit assessment takes place after you start the application.
Home Credit advertises processing or approval “as fast as 1 minute,” but that is a best-case marketing claim rather than a guaranteed processing time for every applicant.
How much can you borrow, and how long can you repay?
Home Credit currently advertises Cash Loans beginning at ₱3,000 and reaching as much as ₱150,000. Your actual maximum and available installment choices depend on the personalized offer generated for your account.
There is an important inconsistency in Home Credit’s own published information. Its July 31, 2026 Cash Loan FAQ says terms can range from 1 to 60 months, depending on the exclusive offer, while a separate May 2026 eligibility article describes flexible Cash Loan repayment plans of 6 to 48 months.
That is a good reason not to treat a general website range as the contract you will actually receive. The relevant numbers are the amount, number of installments, monthly payment, effective interest rate, charges and total repayment displayed in your specific offer and disclosure statement.
What does a Home Credit Cash Loan actually cost?
Do not judge the loan only by the advertised monthly interest rate. Home Credit publishes nominal interest, processing charges, optional protection products and several conditional charges. Your Loan Disclosure Statement should show the figures applicable to your particular contract.
Home Credit’s current disclosures show a Cash Loan nominal interest range of 1.49% to 8.99% per month and cite an average monthly EIR of 3.89% based on a specific example: a ₱45,000 loan over 30 months, 3.80% nominal monthly interest and a ₱500 processing fee. The disclosure says the actual monthly EIR appears on the borrower’s Loan Disclosure Statement.
At the same time, the customer-facing Cash Loan page says the monthly rate starts at 2.32% and varies with the amount, term and customer.
Those figures should not be merged into one assumed rate. They come from different Home Credit disclosures and may reflect different offer structures or eligibility segments.
Other published Cash Loan charges include a processing fee of up to ₱500, Loan Extra Care of up to ₱99 per month, Borrower Protection of up to ₱500 per month, a ₱300 cash-pickup fee, ₱300 for full or partial early repayment, ₱300 to change a due date and ₱50 for an overpayment refund. Optional protection products should be assessed separately from the basic credit cost rather than automatically accepted.
As of September 25, 2026, Home Credit is also advertising a “Triple Zero Triple Saya” promotion running from June 1, 2026 through May 31, 2027 that can waive a ₱500 origination/processing fee for qualifying Cash Loan customers in good standing who receive the required notification. The promotion is targeted, so borrowers should not assume every offer receives the waiver.
Does the Philippine interest-rate cap apply?
For certain small, short-term loans, yes. SEC Memorandum Circular No. 14, Series of 2025 took effect for covered loans from April 1, 2026. Reports on the final SEC rule describe its scope as unsecured, general-purpose loans from financing or lending companies of ₱10,000 or less with a term of four months or less, with a nominal-interest ceiling of 6% per month and an EIR ceiling of 12% per month.
That ceiling should not be misrepresented as applying to every Home Credit Cash Loan. A ₱30,000 loan or a 12-month loan, for example, falls outside those specific size-and-tenor conditions.
How is the Cash Loan released after approval?
Home Credit publishes two principal Cash Loan claiming methods: transfer to a supported bank account or cash pickup through a disbursement partner. For pickup, the company says a valid ID with an address and the reference number are required.
Home Credit warns that a contract can be cancelled if cash requiring pickup is not claimed within seven days. Its fee disclosure separately lists a ₱300 Cash Pick Up Fee, so a borrower considering pickup should confirm whether that charge applies to the specific transaction and how it affects the money actually received.
For bank transfers, the company’s Cash Loan page lists several supported banks, including BPI, BDO, UnionBank, LandBank and Metrobank.
Do not commit the expected loan proceeds to another debt or purchase before the application is approved and the funds have actually arrived.
What happens if you pay a Home Credit Cash Loan late?
Home Credit publishes escalating Cash Loan charges for prolonged non-payment. Because delinquency can become substantially more expensive than the original monthly installment, borrowers should examine both the due-date schedule and the late-payment provisions before signing.
The published Cash Loan fee table lists up to ₱300 at five days past due, up to ₱700 at 30 days and up to ₱1,000 at 60 days. At 90 days of non-payment it lists a termination fee equal to 40% of outstanding principal, followed by an additional 2% of outstanding principal at specified later delinquency stages, plus a published ₱5,000 attorney’s fee where applicable. The precise contractual conditions should be checked in the agreement rather than inferred from the table alone.
Philippine financial consumers also have statutory rights to fair treatment, disclosure and transparency, data protection and complaint handling under Republic Act No. 11765, the Financial Products and Services Consumer Protection Act.
Is Home Credit legitimate and properly identifiable?
Home Credit is not an anonymous loan app. The operating company is HC Consumer Finance Philippines, Inc. Current Home Credit disclosures identify SEC Registration No. CS201301354 and Certificate of Authority No. 1071, and SEC financing-company records independently list the same company and authority number.
That is a more precise statement than calling it simply an “SEC-approved loan app.” Corporate registration, a financing-company Certificate of Authority and the approval of a particular borrower or loan offer are different concepts.
An older SEC list of recorded online lending platforms also identifies HC Consumer Finance Philippines and “My Home Credit,” supporting the connection between the company and its digital lending platform.
Legitimate operation does not mean every offer is inexpensive or appropriate. A borrower still needs to compare the total repayment with the amount actually needed and the ability to make every installment from regular income.
What personal information can the Home Credit app access?
Home Credit’s privacy notice describes relatively broad app permissions. With consent, the app may request access to items including messages, calls, calendar information, contacts, files, installed-app/account-list data, device information and location for fraud prevention, security and eligibility assessment.
Home Credit says transactional or business-to-consumer SMS information may also be processed with consent to evaluate income and spending patterns, while personal and OTP messages are excluded. It says location can be collected for purposes including address verification, serviceability and fraud detection and that permissions can be changed in device settings after an application is submitted, although some app functionality may then be reduced.
Philippine privacy rules are relevant here. NPC Circular No. 2022-02 says online lenders and financing companies should not require unnecessary or excessive app permissions and should stop or allow revocation of access once the relevant purpose has been fulfilled. A March 2026 joint advisory from the NPC, DICT and SEC also reiterated that contacting people in a borrower’s contact list for collection purposes, other than a properly identified guarantor, is prohibited.
Home Credit’s own privacy notice says borrowers can contact its Data Protection Officer about privacy concerns and identifies [email protected] for that purpose.
What should you check before accepting an offer?
The important decision is not simply whether Home Credit finally gives you a Cash Loan offer. It is whether the specific contract gives you enough usable cash at a repayment cost and schedule you can realistically handle without needing another loan.
Start with the Loan Disclosure Statement. Check the approved amount, any deductions or separate fees, monthly installment, number of installments, total repayment, nominal rate, effective interest rate, optional insurance or service charges, due dates and late-payment consequences.
Then verify that the cash-out account belongs to you and that your name and other account details match. Home Credit’s application process asks borrowers to provide identity, income and other personal information, so inaccurate or outdated details can create unnecessary verification problems.
Finally, do not accept optional Borrower Protection or Loan Extra Care merely because they appear inside the application flow. Home Credit itself describes these services as optional. Read the coverage, exclusions and recurring charge first and compare the total repayment with and without the add-on.
FAQ
Can customer service manually give me a Cash Loan offer?
Home Credit’s public documentation does not confirm a process through which customer service can manually create an offer for an otherwise ineligible account. Its published guidance tells customers without an offer to maintain good standing and wait for future eligibility.
I already finished my Product Loan. Why do I still have no Cash Loan offer?
Finishing a Product Loan can make you potentially eligible, but it does not guarantee another offer. Home Credit says offers depend on previous transactions and payment history and does not publish its complete eligibility model.
Can a first-time Home Credit customer apply directly for cash?
Home Credit’s May 2026 eligibility guide says its Product Loan is the loan available to first-time users, while Cash Loan eligibility requires previous use of a Home Credit Product Loan.
If a Cash Loan banner appears, am I already approved?
No. The offer allows you to begin an application. Home Credit states that your selected amount and repayment term still have to be processed for approval.
What if my Cash Loan application is rejected?
Home Credit says a rejected applicant can apply again only after receiving another Cash Loan offer. There is no published guarantee about when – or whether – that next offer will appear.
Final borrower checklist
For someone searching specifically for how to apply for a cash loan in Home Credit without an offer, the key issue is eligibility rather than application technique. Home Credit currently does not publish a legitimate bypass for the offer requirement.
If no offer appears, avoid paying anyone to unlock one. If an offer eventually becomes available, treat it as an invitation to apply rather than money already approved. Read the disclosure before entering the OTP that signs the agreement, calculate whether the monthly payment fits normal income, inspect optional add-ons and permissions, and make sure you understand what happens if a payment is late.
The best point to stop is before signing if the amount actually available, total repayment or due-date schedule does not work for your budget. Receiving an offer creates an option; it does not create an obligation to borrow.
References
- Home Credit Cash Loan FAQ
Organization: HC Consumer Finance Philippines, Inc.
Resource: FAQs: Your Guide to the Home Credit Cash Loan!
URL: Home Credit Cash Loan FAQ - Home Credit Cash Loan Application Guide
Organization: HC Consumer Finance Philippines, Inc.
Resource: Paano Mag-Apply for a Cash Loan sa Home Credit App?
URL: Home Credit application guide - Home Credit Cash Loan Product Page
Organization: HC Consumer Finance Philippines, Inc.
Resource: Cash Loan Philippines: Borrow Up to ₱150K Online
URL: Home Credit Cash Loan page - Home Credit Loan Eligibility Guide
Organization: HC Consumer Finance Philippines, Inc.
Resource: How to Qualify for a Cash Loan, Product Loan, and More Home Credit Offers
URL: Home Credit eligibility guide - Home Credit Disclosures and Fee Schedule
Organization: HC Consumer Finance Philippines, Inc.
Resource: Terms and Conditions / Table of Fees and Charges
URL: Home Credit disclosures - Home Credit Privacy Notice
Organization: HC Consumer Finance Philippines, Inc.
Resource: Home Credit Privacy Notice: For Website and Mobile Apps
URL: Home Credit Privacy Notice - SEC Financing Company Records
Organization: Securities and Exchange Commission Philippines
Resource: List of Financing Companies with Certificate of Authority
URL: SEC financing-company list - Financial Products and Services Consumer Protection Act
Organization: Bangko Sentral ng Pilipinas / Republic of the Philippines
Resource: Republic Act No. 11765
URL: RA 11765 - SEC Memorandum Circular No. 14, Series of 2025
Organization: Securities and Exchange Commission Philippines
Resource: Recalibrated Ceilings on Interest Rates and Other Fees Charged by Financing Companies and Lending Companies
URL: SEC MC No. 14, Series of 2025 - Loan-Related Data Privacy Rules
Organization: National Privacy Commission
Resource: NPC Circular No. 2022-02, Amending NPC Circular No. 20-01
URL: NPC Circular No. 2022-02 - 2026 Joint Advisory on Online Lending Platforms
Organization: National Privacy Commission, DICT and SEC
Resource: Advisory on Online Lending Platforms to the Public
URL: 2026 Online Lending Platforms advisory