Last Updated on 23/09/2026 by Nicole Alba
A loan app can advertise a surprisingly low monthly rate and still produce a much more expensive loan than you expected. The problem is not always the interest rate itself. Processing fees, documentary stamp tax, service charges, the way interest is calculated, and deductions made before disbursement can materially change what you receive and what you eventually repay.
There is another complication in the Philippines: the app name you see on your phone may not be the legal entity providing the credit. A bank loan is generally under Bangko Sentral ng Pilipinas (BSP) supervision, while lending and financing companies fall under the Securities and Exchange Commission (SEC). With products such as GLoan, even the lender assigned to a particular account may need to be confirmed from the disclosure statement.
This review compares currently published terms from several established digital borrowing options rather than assuming that the smallest advertised percentage automatically means the cheapest loan.
As of September 2026, several legitimate digital lenders and banks publish relatively competitive starting rates. Maya Personal Loan advertises rates from 0.77% monthly add-on, RCBC Digital Personal Loan publishes 0.90% – 1.10% monthly add-on for qualified customers, and CIMB lists 1.12% – 1.95% monthly add-on. GLoan starts at 1.59% monthly but also deducts a 3% – 5% processing fee. The percentages are not directly comparable because lenders use different rate structures. Before accepting any offer, check the effective interest rate, net proceeds, total repayment, fees, late-payment terms, and legal lender named in your disclosure statement.
| Borrower question | Current finding | Why it matters |
|---|---|---|
| Which product has one of the lowest published starting add-on rates reviewed here? | Maya Personal Loan publishes rates as low as 0.77% monthly add-on for a 24-month term. | The actual offer is subject to credit evaluation and must be checked in the disclosure statement. |
| Is RCBC Digital Personal Loan competitively priced? | Qualified RCBC customers may receive 0.90% – 1.10% monthly add-on offers. | It is not an open offer for every app user; eligibility is customer-specific. |
| What does CIMB publish? | 1.12% – 1.95% monthly add-on, with loans from ₱30,000 to ₱1 million and terms from 12 – 60 months. | A longer term may reduce the monthly installment while increasing the time you remain in debt. |
| Is GLoan’s headline rate the whole cost? | No. GLoan lists 1.59% – 6.99% monthly interest plus a 3% – 5% processing fee deducted from proceeds. | The approved principal can be higher than the cash actually received. |
| Does UNO disclose an effective rate? | Yes. #UNOnow publishes a 1.79% monthly add-on starting rate, while its table shows annual EIRs roughly 45.42% – 57.22%, depending on tenor. | This illustrates why an add-on rate should not be compared directly with an EIR. |
| Are short small loans subject to a general 12% monthly cap? | Only certain SEC-regulated unsecured general-purpose loans of ₱10,000 or less with terms up to four months fall within the 2026 recalibrated ceiling. | The cap should not be misrepresented as applying to every personal loan in the Philippines. |
| Where should regulatory complaints go? | BSP-supervised institutions can be escalated through BSP consumer channels after contacting the institution first; lending-company complaints fall under the SEC. | Using the correct regulator can make complaint handling more effective. |
Review methodology: Published bank and lender disclosures, current regulatory information, fee schedules, and product pages were checked rather than claiming an unverified hands-on borrowing test.
Is a “legit loan app” automatically a low-interest loan app?
No. Regulatory legitimacy and affordability answer two different questions. A lender may be identifiable and properly regulated while still offering an expensive loan. The right comparison is therefore not simply “legit versus scam,” but also total borrowing cost, net proceeds, repayment term, penalties, and affordability.
For bank products, borrowers can use the BSP’s institutional verification resources to check whether the provider is supervised by the central bank. The SEC separately maintains regulatory information, advisories and records for financing companies, lending companies and online lending platforms. In August 2026, the SEC again issued an advisory concerning unauthorized online lending platforms, reinforcing the need to verify the entity rather than trusting an app-store listing alone.
This distinction matters because phrases such as “SEC registered” can be misleading when used casually. Corporate registration does not by itself mean every lending activity or every online platform operated under that company’s name has all required authority.
The SEC specifically advises borrowers to verify the lending or financing company and its online lending platform, read the loan agreement, examine interest and fees, and be cautious about unnecessary permissions involving phone contacts or social-media data.
Which legitimate loan apps currently publish comparatively low rates?
Among the products reviewed, some of the smallest published starting add-on rates come from bank-based personal loans rather than short-term cash-loan apps. Maya, RCBC and CIMB publish starting add-on rates below many app-based small-loan products, although eligibility, fees and rate calculations differ substantially.
Maya Personal Loan
Maya Bank currently advertises Personal Loan offers from ₱15,000 to ₱250,000, with terms of 6 to 24 months. Its published starting price is 0.77% monthly add-on for a 24-month loan, equivalent in Maya’s disclosure example to about 1.40% monthly effective interest. The actual rate and corresponding EIR are shown in the Maya app and disclosure statement.
Maya currently describes the service fee and documentary stamp tax for its Personal Loan as waived under an early-access arrangement. That point is worth rechecking immediately before borrowing because promotional fee structures can change.
Maya’s own ₱25,000 example is particularly useful. At a 0.83% monthly add-on rate over six months, it shows monthly installments of approximately ₱4,374.17 and total repayment of ₱26,239.19.
RCBC Digital Personal Loan
RCBC’s Digital Personal Loan page states that qualified RCBC customers may receive a monthly add-on rate of 0.90% to 1.10%. The processing fee is 1% of the amount availed or ₱1,500, whichever is higher, capped at ₱5,000, and is deducted from loan proceeds.
The qualification point is important. This particular digital offer is described for RCBC depositors and home-loan borrowers who meet the bank’s credit criteria, with individual loan amounts shown through RCBC Pulz. It should therefore not be interpreted as a 0.90% loan that any new applicant can automatically obtain.
RCBC’s wider Personal Loan program publishes loan amounts from ₱20,000 up to ₱5 million, with terms from three to 60 months.
CIMB Personal Loan
CIMB currently publishes monthly add-on rates from 1.12% to 1.95%, corresponding to contractual annual rates of 24%, 30% or 36%. Available Personal Loans range from ₱30,000 to ₱1 million, with terms of 12 – 60 months.
CIMB’s fee structure illustrates why disbursement destination matters. Its current FAQ lists no disbursement fee when proceeds go to a CIMB account, but a fee of 1% of principal or ₱500, whichever is higher, for disbursement to another bank. Documentary stamp tax also applies. Late payments can attract 5% of the unpaid installment or ₱300, whichever is higher, while early settlement can cost 3% of the unbilled amount or ₱300 minimum.
For applicants focused on cost, those charges belong in the comparison alongside the interest rate.
UnionBank Personal Loan
UnionBank uses a different pricing presentation. Its current online calculator illustrates loans using an average 26.9% Annual Contractual Rate (ACR) and offers amounts up to ₱2 million, with repayment periods extending to five years.
The page also shows why comparing only “monthly rates” can be misleading. UnionBank’s fee table gives an example of a ₱200,000 loan over 36 months with a 26.9% ACR and an EIR of about 31.98%, after incorporating interest, the disbursement fee and applicable DST.
UnionBank currently charges a ₱1,750 disbursement fee, plus applicable documentary stamp tax. Its late charge is ₱500 or 6% of the overdue amount, whichever is higher.
UNO Digital Bank #UNOnow
UNO’s #UNOnow loan currently offers ₱15,000 to ₱250,000 for six to 36 months. Its advertised monthly add-on rate starts at 1.79%.
UNO deserves attention because it publishes both the attractive-looking add-on rate and a much more informative EIR table. Depending on tenor, the page lists annual effective rates of roughly 45.42% to 57.22%.
The product also deducts a processing fee of 3% of the loan or ₱500, whichever is higher, plus applicable DST before release. This means the borrower can receive less cash than the approved principal while interest calculations still relate to the loan contract.
That is exactly the type of difference borrowers should identify before tapping “Accept.”
GCash GLoan
GLoan is convenient because it sits inside an app already used by many Filipinos, but its cost range is wide. GCash currently publishes loan amounts from ₱500 to ₱150,000, monthly interest between 1.59% and 6.99%, and a 3% – 5% processing fee deducted from the money released.
The upper end of that range is materially different from the starting 1.59% figure.
GLoan also demonstrates why the brand on the screen is not necessarily the lender named in the contract. GCash states that GLoan works with third-party financial institutions and directs borrowers to their Disclosure Statement to determine whether the account is with Fuse Financing Inc. or another partner financial institution.
For repayment, paying directly through the GLoan dashboard is posted instantly, while some Pay Bills and payment-partner transactions can take up to three business days to reflect. Borrowers paying close to the deadline should take that posting difference seriously.
Tonik loans
Tonik’s small-loan pricing is less competitive on headline rate than the bank personal loans above. Its Credit Builder product advertises loans up to ₱50,000 with six-, nine- or twelve-month terms and a monthly add-on rate advertised as low as approximately 4.20% on the current loans page.
Tonik also publishes a Flex XL product with a monthly add-on rate that can be as low as 2.01% and terms extending to 24 months, but access can depend on an offer appearing in the customer’s Tonik app.
For the former Quick Loan/Credit Builder structure, Tonik’s FAQ lists a ₱500 processing fee and applicable documentary stamp tax deducted at disbursement.
Why can a 0.77% loan be more expensive than it sounds?
Because “monthly add-on rate” is not the same thing as an effective monthly interest rate. Add-on interest is calculated against the original principal even as the borrower gradually repays that principal. EIR reflects the economics of the payment stream more accurately and is usually the better comparison tool.
Consider Maya’s current disclosure. A starting rate of 0.77% per month sounds extremely small, but Maya itself states that this can correspond to roughly 1.40% monthly effective interest for its referenced 24-month offer.
UNO makes the difference even more visible. Its 1.79% monthly add-on offer corresponds to annual EIR figures above 45% in its published table.
This does not mean either disclosure is deceptive. They are simply different measurements. Problems begin when borrowers – or comparison websites – put a monthly add-on rate beside an annual EIR and treat them as if they measure the same thing.
A sound comparison should use the same metric whenever possible.
How much money will you actually receive?
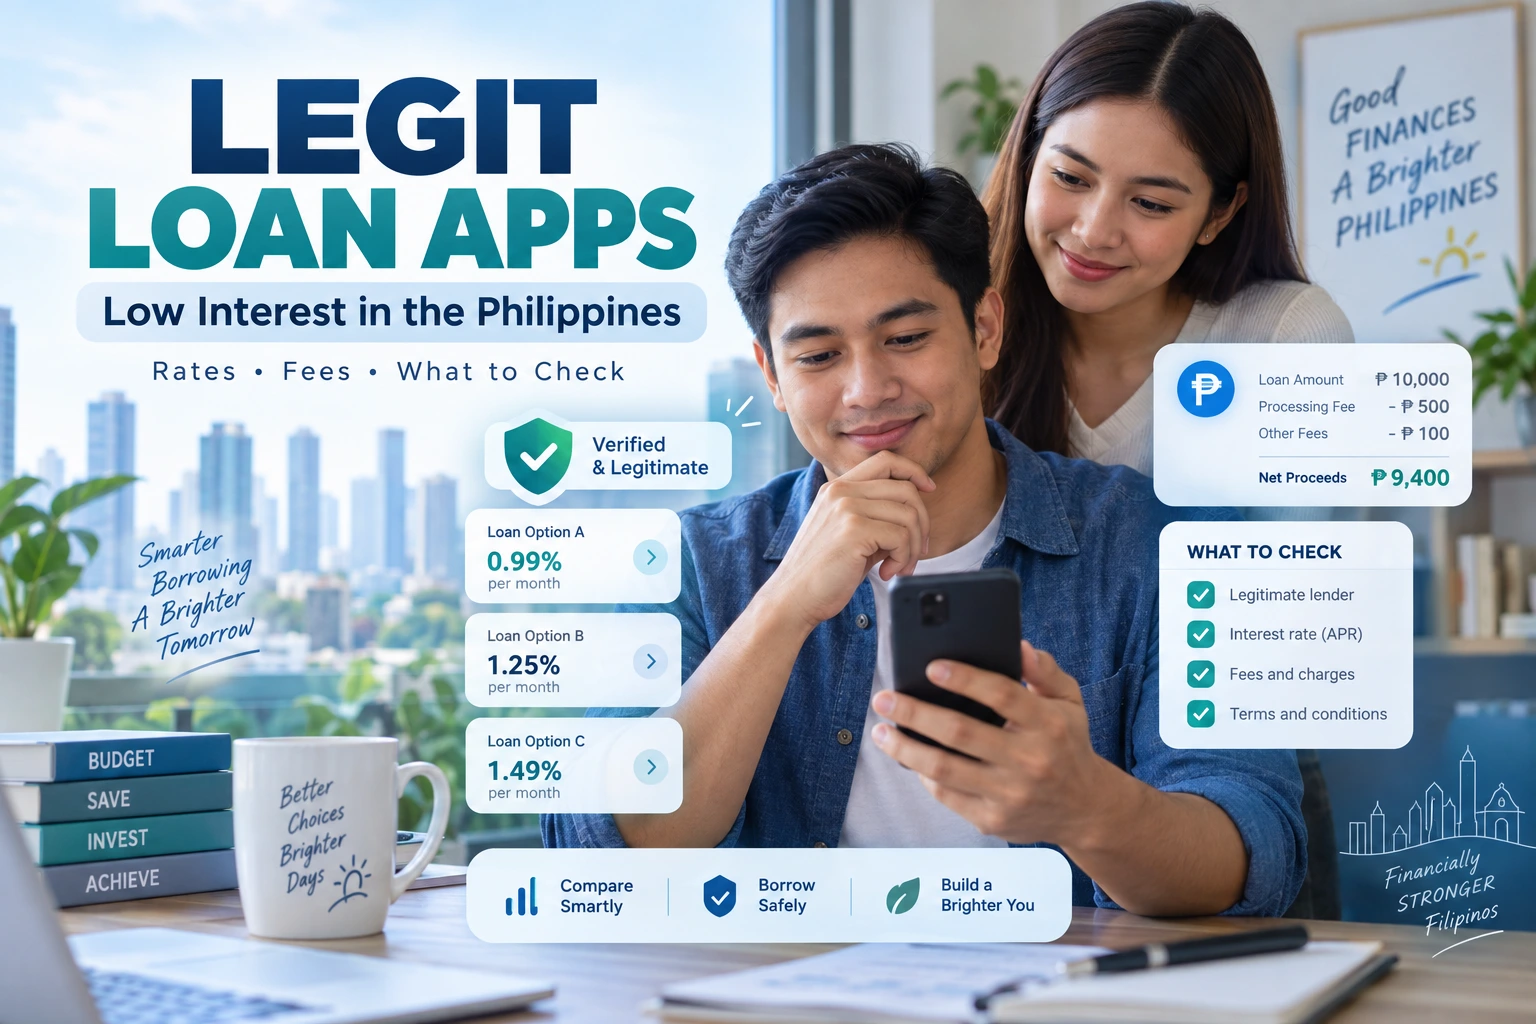
Start with net proceeds, not the approved loan amount. A ₱20,000 approval does not necessarily mean ₱20,000 reaches your wallet or bank account. Processing fees, DST or other permitted deductions may be taken before disbursement.
GLoan makes this particularly easy to illustrate. If the processing fee on an offer were 5%, then a ₱20,000 approved principal would involve a ₱1,000 processing deduction before considering any other applicable contract terms. The borrower’s usable cash would therefore be lower than the face value of the loan. GCash currently publishes processing fees between 3% and 5%.
UNO similarly deducts its 3% or ₱500-minimum processing charge and applicable DST before releasing proceeds.
RCBC’s digital loan also deducts its applicable processing fee from proceeds.
The practical calculation is:
Approved principal − upfront deductions = cash actually received
Then compare:
Total repayments − cash actually received = real peso cost to obtain that cash
That second number can tell you more than the advertisement.
What Philippine interest-rate limits apply in 2026?
The widely quoted Philippine loan-rate cap is not a universal ceiling on every personal loan. From April 1, 2026, the recalibrated SEC rules apply specifically to qualifying unsecured general-purpose loans from lending and financing companies of ₱10,000 or less with terms not exceeding four months.
SEC Memorandum Circular No. 14, Series of 2025 was issued on December 10, 2025. For covered loans entered into, renewed or restructured beginning April 1, 2026, the framework maintains a 6% monthly nominal interest ceiling, reduces the applicable monthly EIR ceiling to 12%, caps late-payment/nonpayment penalties at 5% per month on the outstanding scheduled amount due, and retains a total-cost cap equivalent to 100% of the amount borrowed.
The scope matters. A ₱200,000 bank personal loan with a 24-month term is not the same category as a ₱5,000 four-week online lending-company loan.
Applying the 12% figure indiscriminately to every Philippine loan would therefore be inaccurate.
What rights do borrowers have?
Philippine financial consumers have statutory rights involving disclosure, fair treatment, data privacy, complaint handling and protection against abusive practices. Those rights do not erase a valid debt, but they affect how a financial service provider must disclose, service and collect it.
Republic Act No. 11765, the Financial Products and Services Consumer Protection Act, recognizes rights to fair treatment, disclosure and transparency, protection of consumer assets, data privacy, and timely complaint handling. It also prohibits abusive debt-collection practices by covered financial service providers.
The National Privacy Commission, SEC and DICT have also reiterated data-protection requirements for entities offering or facilitating loans through online lending platforms.
For SEC-supervised lending and financing companies, the SEC has separate rules against unfair debt-collection practices.
If a complaint concerns a BSP-supervised institution, the borrower should first raise it with the institution’s consumer assistance mechanism. Unresolved matters may then be escalated through BSP Online Buddy or other BSP Consumer Assistance Mechanism channels.
For lending-company complaints, the SEC’s Financial and Lending Company Division is the relevant regulatory channel.
What should you check before accepting an online loan?
Do not decide from the banner showing “as low as” interest. Open the disclosure statement and reconstruct the transaction from beginning to end: who is lending, how much cash arrives, how much leaves your pocket later, and what happens if anything goes wrong.
Before confirming a loan, check these seven items:
- Legal lender: identify the bank, lending company or financing company named in the contract – not merely the app brand.
- Net proceeds: confirm exactly how much will be transferred after deductions.
- Effective interest rate: use the EIR when available rather than relying solely on an add-on or nominal rate.
- Total repayment: add every scheduled installment, not just the first monthly payment.
- Fees and taxes: check processing, disbursement, DST, service and pretermination charges.
- Late-payment formula: understand whether penalties are fixed, percentage-based, daily or monthly.
- Posting time: confirm when a repayment is considered received, particularly when paying through third-party channels.
The SEC’s borrower advisory makes the same fundamental point: read the agreement, verify the platform and provider, review charges and due dates, and avoid granting unnecessary access to phone contacts or social-media information.
How fast are legitimate loan apps?
“Fast” usually describes a best-case workflow, not a guaranteed disbursement time. Credit evaluation, identity checks, income documentation, employer verification, account matching and payment-rail delays can all affect the actual timeline.
UnionBank says a complete Personal Loan application may be processed in as fast as 24 hours, while also making approval subject to its credit standards.
Tonik’s Quick Loan FAQ historically states approval can occur within around two days if the borrower completes identity verification, while Flex XL can require further checks such as employer verification.
CIMB requires applicants to meet age, income and employment or self-employment criteria; its current eligibility information specifies a minimum gross monthly income of ₱15,000 and other employment-history conditions.
These requirements are why “instant loan” should never be interpreted as guaranteed approval.
FAQ
Can I choose a loan solely because it has the lowest monthly add-on rate?
No. Compare EIR, net proceeds, total repayment and fees. A product with a slightly higher headline rate but fewer deductions can sometimes produce a lower real peso cost than an offer with a lower advertised rate and substantial upfront charges.
Is an app safe because it appears in Google Play or the Apple App Store?
App-store availability is not sufficient regulatory verification. For non-bank online lenders, check the SEC’s current records and advisories. For banks and BSP-supervised entities, use official BSP verification resources. The SEC was still publishing warnings about unauthorized online lending platforms in 2026.
Does “0% interest” mean borrowing is free?
Not necessarily. A product may charge no conventional interest while still imposing service fees, transaction charges or other permitted costs. Maya Easy Credit, for example, advertises no interest but currently has a service fee starting at 3.99% plus applicable DST.
Can paying early reduce my loan cost?
It depends on the contract. Some products may provide an interest rebate, while others impose pretermination or early-settlement fees. GCash states that qualifying GLoan borrowers who fully pay at least one month before the due date may receive interest cashback, while CIMB currently lists an early-settlement charge.
What if the loan app threatens or publicly shames me over a debt?
Keep records of messages, calls and screenshots and raise the issue with the provider through its formal complaint channel. Depending on the provider, unresolved complaints may be escalated to the SEC or BSP. Philippine financial-consumer rules do not give lenders unrestricted authority to use abusive collection methods.
Which loan should you compare first?
The useful question is not simply, “Which app has the lowest interest?”
Start with four numbers displayed in the actual offer you receive:
cash you will receive → monthly payment → number of payments → total repayment
Then check the EIR and every upfront or late-payment fee.
For borrowers who qualify, bank-based personal loans such as Maya Personal Loan, RCBC Digital Personal Loan and CIMB currently publish lower starting add-on rates than several small cash-loan products reviewed here. Yet published minimum rates are not guaranteed offers, and differences in fees and calculation methods prevent a fair comparison based on headline percentages alone.
GLoan may be convenient for eligible GCash users, but its 1.59% – 6.99% monthly rate range and 3% – 5% upfront processing deduction mean the specific offer deserves close inspection.
UNO provides a useful lesson because its disclosure shows how a 1.79% monthly add-on rate can translate into a much higher annual EIR.
Before proceeding, make sure the repayment can come from income you reasonably expect to have – not from another loan. If repayment depends on immediately borrowing again, the apparently convenient loan may be creating a more expensive cash-flow problem rather than solving the original one.
References
- Securities and Exchange Commission Philippines
Organization: Securities and Exchange Commission
Resource: SEC MC No. 14, Series of 2025 – Recalibrated Ceilings on Interest Rates and Other Fees Charged by Financing Companies and Lending Companies
URL: SEC Memorandum Circular No. 14, Series of 2025 - Securities and Exchange Commission Philippines
Organization: Securities and Exchange Commission
Resource: Advisories and Notices – Lending and Financing Companies
URL: SEC Lending and Financing Company Advisories - Bangko Sentral ng Pilipinas
Organization: Bangko Sentral ng Pilipinas
Resource: BSP Financial Institution Verifier
URL: BSP Financial Institution Verifier - Republic Act No. 11765
Organization: Republic of the Philippines / Lawphil
Resource: Financial Products and Services Consumer Protection Act
URL: Republic Act No. 11765 - Maya Bank
Organization: Maya Bank, Inc.
Resource: Borrow Money Online – Maya Easy Credit and Personal Loan
URL: Maya Bank Borrow Products - CIMB Bank Philippines
Organization: CIMB Bank Philippines, Inc.
Resource: Personal Loan Help and FAQs
URL: CIMB Personal Loan Information - UnionBank of the Philippines
Organization: UnionBank of the Philippines
Resource: Personal Loan
URL: UnionBank Personal Loan - UNO Digital Bank
Organization: UNO Digital Bank
Resource: #UNOnow Online Bank Loan
URL: UNO Digital Bank Loans - GCash Help Center
Organization: GCash
Resource: GLoan Fees and Interest Rate
URL: GCash GLoan Fees and Interest Rate - GCash Help Center
Organization: GCash
Resource: Who Is the Lender of My GLoan?
URL: GLoan Lender Information - Tonik Bank
Organization: Tonik Digital Bank, Inc.
Resource: Tonik Loans
URL: Tonik Bank Loans - RCBC
Organization: Rizal Commercial Banking Corporation
Resource: RCBC Personal Loans
URL: RCBC Personal Loans - National Privacy Commission
Organization: National Privacy Commission
Resource: Joint Advisory on Online Lending Platforms
URL: National Privacy Commission - Bangko Sentral ng Pilipinas
Organization: Bangko Sentral ng Pilipinas
Resource: Consumer Assistance Channels and BSP Online Buddy
URL: BSP Consumer Assistance Channels